Ukraine's Grid Blocks Power
8 stories · ~7 min read
Listen
If You Only Read One Thing
Ukraine has enough electricity and still can't keep its capital supplied. Zelenskyy's account of the damaged grid explains why adding generation won't solve that shortage. Berkshire's earnings reveal a separate problem: GEICO is attracting customers while keeping less of their premiums. Both stories make growth figures less reassuring when the cost of maintaining the service is rising underneath them.
Ukraine Has Electricity Its Grid Can't Deliver
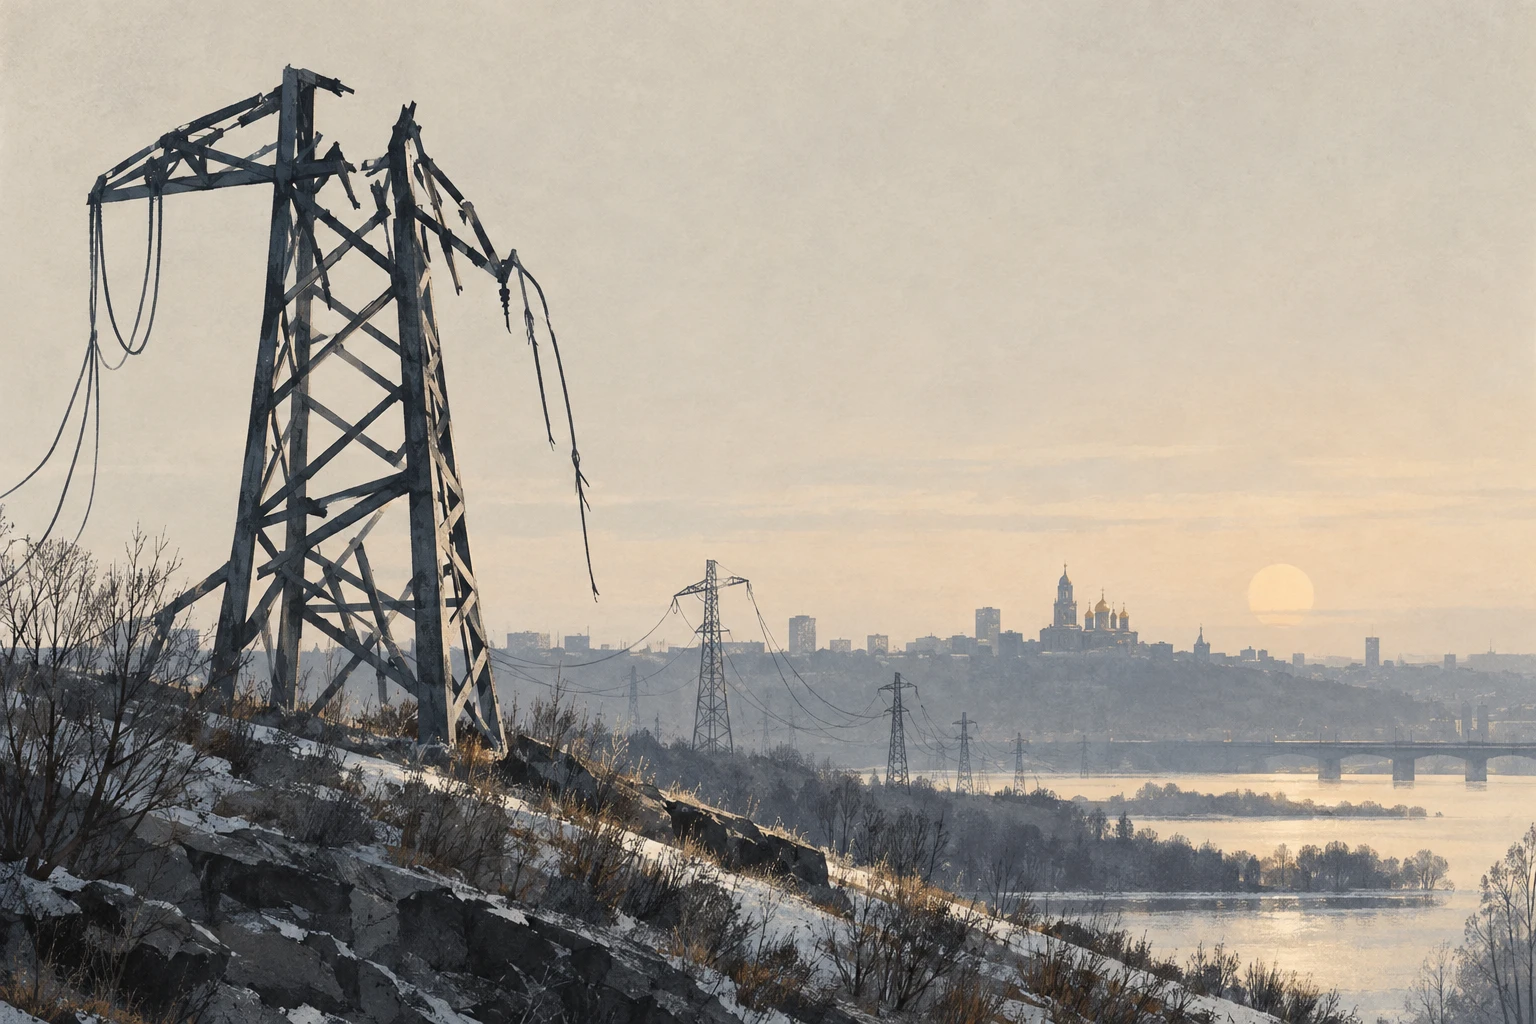
Ukraine's immediate electricity shortage is a delivery problem. In his November 7 address, President Volodymyr Zelenskyy said the country was generating more electricity than it consumed. Russian attacks on substations and transmission lines nevertheless left Kyiv and other regions facing severe shortages.
That changes what help accomplishes. Another generator adds potential output. A repaired substation reconnects existing output to homes and factories. An interceptor can keep the repaired substation from being destroyed again. The three purchases serve different purposes; counting them together as energy assistance hides whether the package can restore dependable service.
The damage is continuing across the energy system. Naftogaz says Russia targeted one of its central Ukrainian oil and gas facilities three times overnight. Its dated news index confirms the repeated attacks. Those attacks threaten a different part of the energy system from electricity transmission; they aren't a measure of how much power Kyiv lost.
This is a material deterioration from Ukraine's offer to exchange refinery restraint for Patriot supplies. That proposal treated air defense as something Washington could deliver to make restraint worthwhile. The latest attacks show the cost of waiting: functioning generation can become unusable when the connections around it are hit.
Russia is also attacking the transport that supports recovery. The Institute for the Study of War's November 7 assessment documents damage to Kyiv's Northern Bridge and places the barrage ahead of planned November 10–11 talks in Abu Dhabi. Repair crews and replacement equipment depend on logistics too. Destroying a connection can therefore interrupt today's service and slow tomorrow's repair.
A negotiated pause could reduce that burden faster than additional construction. But entering talks doesn't itself protect a substation. Ukraine needs the pause to hold, or enough protection and repair capacity to keep essential connections working while attacks continue.
For the next one to two years, I'd favor qualified air-defense and grid-repair suppliers over a broad Ukrainian generation-rebuilding bet. They address the immediate constraint, although procurement terms still decide their profits. It's the same lesson that keeps recurring in compute infrastructure: extra capacity has limited value when another necessary input is missing. A sustained ceasefire or restored transmission would weaken that preference. Kyiv's power shortages shrinking while national generation remains in surplus would show that the recovery is reaching the right equipment.
Berkshire Buys Shares as GEICO's Margins Shrink
Berkshire is spending on its own shares while its largest auto insurer earns less from the business it writes. The combination puts two different judgments beside each other: management sees value in the conglomerate, but GEICO's customer growth is getting more expensive.
Berkshire repurchased $9.6 billion of stock in the third quarter. Its earnings release reports operating profit of $12.705 billion, down from $13.485 billion a year earlier, a decline of 5.8%. That measure strips out investment gains and losses, so the deterioration can't be dismissed as stock-market accounting.
GEICO's numbers explain part of the problem. Its quarterly filing shows earned premiums rising 1.3%, while claims and related expenses rose 8.5%. More policies were in force, but average premiums per policy were lower. Customers were buying coverage on terms that left GEICO absorbing more of the claims bill.
For every $100 of earned premiums, GEICO spent $91.40 on claims and underwriting expenses, against $84.30 a year earlier. That left $8.60 before investment income, compared with $15.70. The business remained profitable, but the amount retained from each premium dollar fell sharply. More customers won't automatically reverse that arithmetic.
Customer acquisition explains some of the pressure. Berkshire's filing attributes the higher nine-month expense ratio primarily to commissions and advertising. That spending can depress current profit while building a valuable renewal book. Yet future renewals need to repay the upfront cost. Higher claims costs make that repayment harder even after the advertising bill has been paid.
Berkshire's diversified earnings give it room to finance that experiment. An insurer with less capital might have to choose between defending policy count and preserving capital. Berkshire can also retire shares when management believes the price is attractive. That flexibility is an advantage over the next 12–24 months, and I'd favor it over insurers whose expansion depends on consistently benign claims costs.
That isn't a reason to pay any price for Berkshire. Its buybacks reflect management's valuation judgment, and the operating weakness is real. The broader pattern is familiar from Apple's recent results: higher activity helps owners only when the company keeps enough after paying its suppliers and obligations. GEICO's next reported claims ratio falling below 76.6%, without another decline in average earned premiums, would support the case that growth is becoming more profitable.
The Contrarian Take
Everyone says: A growing cash pile means a company isn't putting money to work.
Here's why that's wrong: Berkshire ended September with about $377.4 billion in consolidated cash, cash equivalents and Treasury bills, after repurchasing $9.6 billion of shares during the quarter. Cash is a balance after money comes in and goes out; it isn't a spending total. A company can generate more than it deploys and still invest heavily. Berkshire also reports a narrower $352.3 billion measure for insurance and other businesses, net of certain purchase payables. Mixing those definitions makes the supposed message from management even less reliable. The buybacks reveal a willingness to invest at prices available during the quarter. A large ending balance doesn't cancel that decision.
Under the Radar
-
Washington is asking Beijing to implement an existing bargain. Treasury's November 6 readout says Scott Bessent pressed He Lifeng for immediate implementation of the Busan commitments. That's a different negotiating problem from announcing another agreement: exporters need the existing terms to work. A leader-level meeting can preserve relations while companies continue waiting for the permissions that turn a diplomatic promise into a shipment.
-
AWS's migration shortcut has a maintenance bill. Its November 6 Babelfish notice describes two security defects in the layer that lets SQL Server applications use PostgreSQL. Aurora customers must upgrade affected clusters and apply maintenance. Compatibility makes switching databases easier, but the vendor still has to maintain the software that makes the substitution work. The savings from leaving one platform aren't the whole cost of operating its replacement.
Quick Takes
-
Nvidia's China approvals face a buyer-verification problem. A New York Times investigation, summarized by The Verge, found approved H200 handlers with empty offices and links to blacklisted firms. These are reported findings, not a ruling that chips were diverted. The commercial exposure is broader than one questionable buyer: doubts about vetting can threaten the licensing route used by legitimate customers too. Supplier access increasingly depends on proving who receives the hardware. (Source)
-
Democrats have named their AI agenda. Reuters reports planned bills on data-center electricity costs, independent model testing and liability. This advances the post-election shift from an electoral result to specific proposals. Trump's opposition makes passage difficult, but committees can demand testimony before a bill becomes law. Companies face a nearer prospect of explaining their economics and failures publicly than of complying with a settled national regime. (Source)
-
Microsoft can leave GPUs that still work. Bloomberg reports Microsoft is winding down its Oracle compute rental because older hardware no longer suits its changing needs; Oracle says demand for earlier-generation GPUs remains strong. Both can be true. A GPU can keep running after Microsoft stops renting it. Oracle still needs another paying customer. Oracle's ability to relet that capacity matters more than the departing customer's identity alone. (Source)
-
Iran's blockade is still being enforced with force. US Central Command says an American aircraft disabled a commercial cargo ship in the Gulf of Oman on Saturday after it tried to breach the blockade. AP and Reuters report the incident, a further escalation beyond yesterday's explosions. For shippers, negotiations haven't yet produced dependable passage; military enforcement continues to interrupt commercial voyages. (Source)
The Thread
More spending can be required simply to preserve the service already being sold. Ukraine replaces damaged connections to deliver electricity it can already generate. GEICO pays more to settle claims on coverage it has already promised. Oracle may need to refresh or reassign machines to keep a customer paying. These are different causes, but they create a shared trap when interpreting an investment boom: money spent on replacement can look like money spent on expansion. Suppliers may enjoy strong orders while their customers gain little additional earning capacity. That makes replacement demand a possible source of durable supplier revenue, alongside a reason to be cautious about the buyers' returns. The useful comparison is between spending and the additional service it produces, after the existing service has been maintained.
Predictions
New predictions:
- I predict: GEICO's full-year 2026 combined ratio, measuring claims and underwriting expenses as a share of earned premiums, will exceed its 2025 full-year ratio. (Confidence: medium; Check by: 2027-03-01)
2026-11-08 · 03:25 EST
Tomorrow morning in your inbox.
Subscribe for free. 10-minute read, every weekday.